Session Summary
Power is unevenly distributed across states, and competing interests make international relations more complex than a contest with clear winners and losers.
Conflict and competition are enduring features of international relations. Be cautious against treating exceptional periods of relative stability as the permanent norm. Understanding the historical processes behind events helps governments and investors maintain perspective and avoid overreacting as a response.
States draw on different strengths to protect their interests and increase their bargaining power. US-China competition unfolds within fluid alignments across countries and sectors, reminiscent of the interbellum period, with China’s industrial and trading strength coexisting with US financial dominance. Governments increasingly use industrial policy to strengthen their strategic advantages, secure supply chains and reduce vulnerabilities, while making their economies harder to replace.
Middle and smaller powers can exercise meaningful influence through specialised capabilities and economic credibility. For instance, Malaysia and Singapore’s roles in semiconductors and data centres demonstrate their importance within sectors where larger powers compete. Malaysia’s fiscal credibility provides a further advantage, while access to stable funding remains an important consideration for countries without reserve currencies.
Concentration in US financial markets and AI investment raises economic risks and tests institutions’ ability to respond.
The scale and concentration of US financial markets magnify the economic consequences of a sustained correction. With US equities valued at roughly 250% of GDP, a lasting 25–30% correction would erase equity value equivalent to ~62.5-75% of annual GDP. Growing dependence on asset wealth means such losses could affect spending, investment and confidence, making market shocks more consequential for the wider economy and testing institutions’ capacity to respond.
AI expands opportunity while concentrating control, but building capability does not guarantee lasting returns. Young entrepreneurs can build businesses with smaller teams, while costly data centres and power grids favour large providers and may draw greater state involvement, particularly in China. The sustainable level of spending remains uncertain, creating risks of overcapacity.
The shift towards an economy driven by asset wealth is deepening inequality and dependence on financial markets. Asset wealth has grown faster than labour income, with the wealthiest 1% of Americans holding roughly US$55 trillion, comparable to the bottom 90% combined. These uneven gains can sustain populist pressures across the political spectrum, while growing reliance on equity wealth makes a lasting market correction more consequential for the wider economy.
Investors should anchor asset allocation in the 6Ds and prepare portfolios for higher yields, inflation and volatility.
Six structural forces should anchor investment decisions. The 6Ds are namely deficits, decarbonisation, depopulation, deregulation, deglobalisation, and de-dollarisation. In the short term, deficits are the most important force, whereas demographic pressures are an underestimated risk.
The most debated risks may not necessarily be the most consequential. While financial markets are concerned about deglobalisation and de-dollarisation, US financial dominance has persisted amidst rerouted trade. Enthusiasm for AI spending could divert attention from tariff increases, renewed conflict and fiscal pressures, while the returns on that spending remain uncertain.
Long-term investment decisions should distinguish structural pressures from momentum-driven market swings.The outlook points to higher inflation, larger fiscal deficits and greater macroeconomic volatility as the backdrop for investment decisions. In the short term, algorithmic trading and ETF flows can amplify momentum-driven sell-offs, producing market movements that extend beyond what changes in fundamentals alone would justify.
Quotes
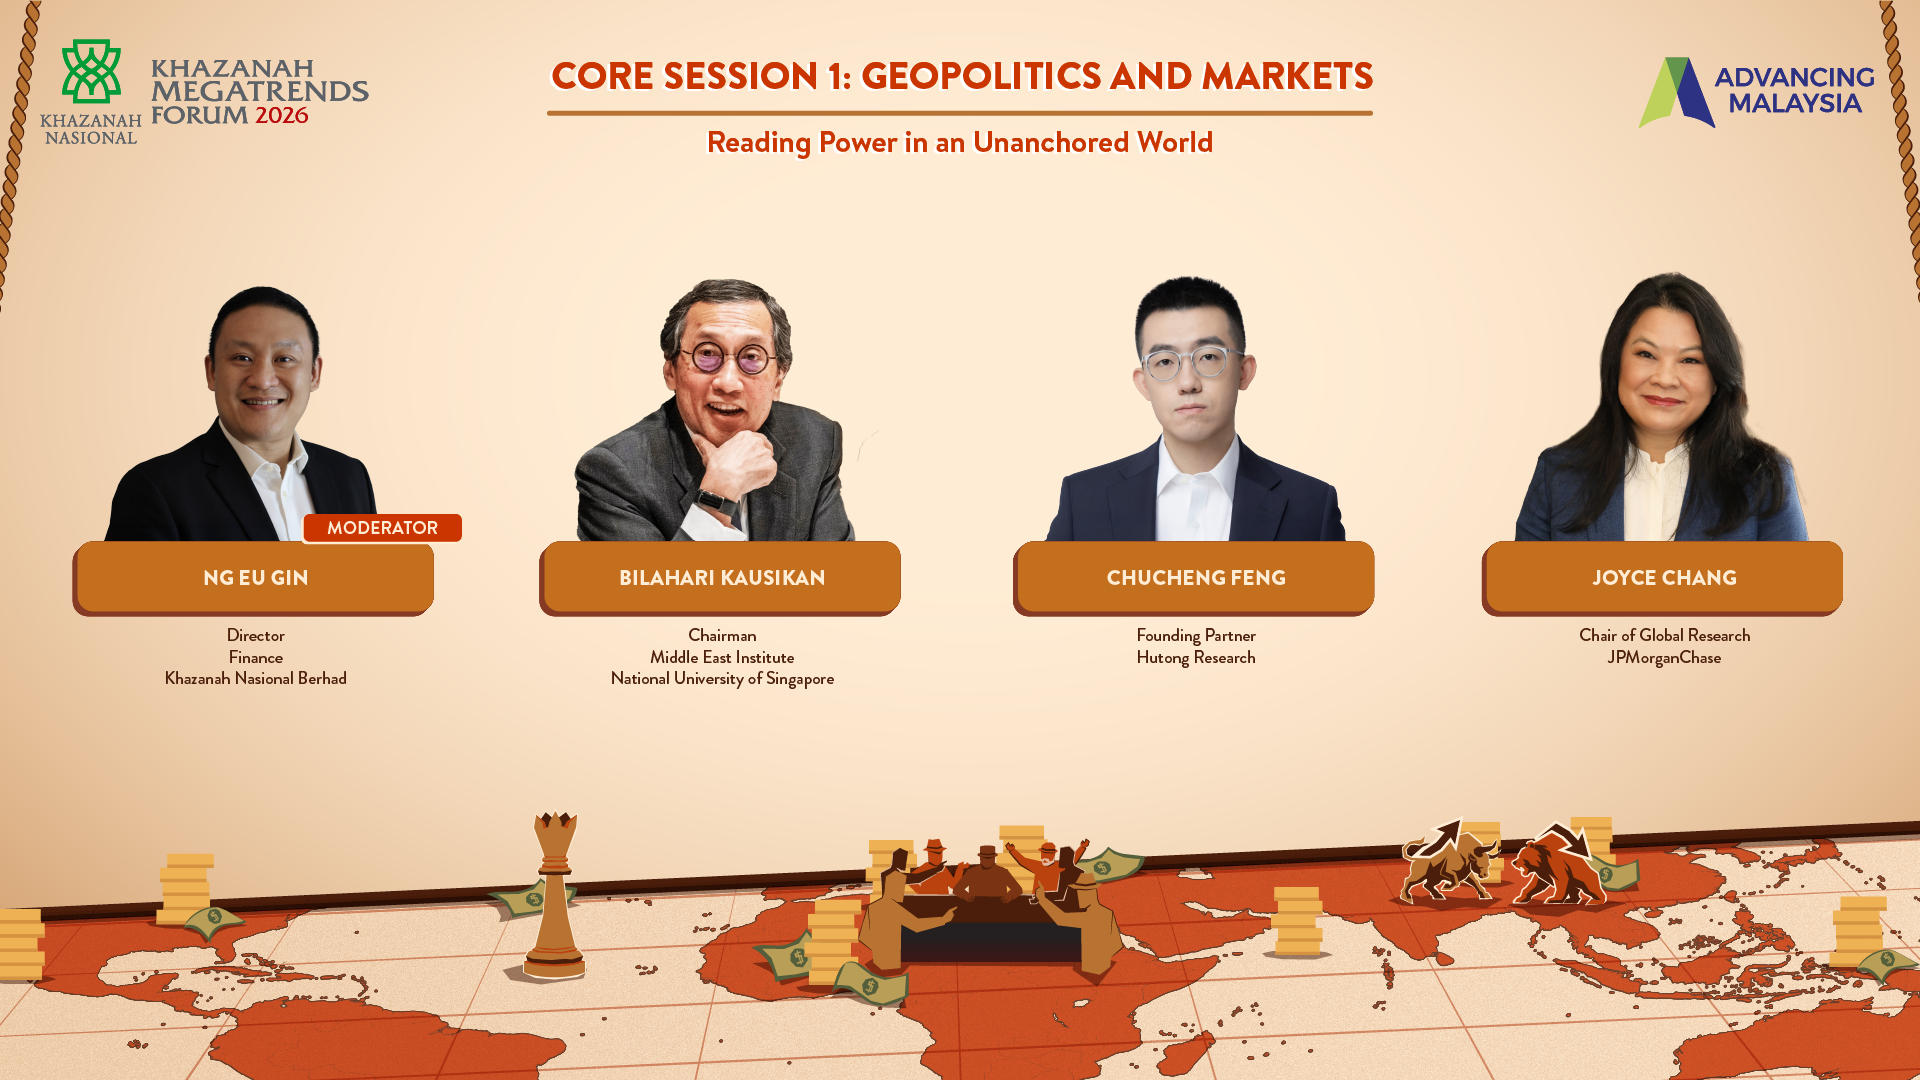
“Every country has two foreign policies: a foreign policy of theology where we always stand for the highest principles, and a foreign policy of practical diplomacy in which principles more often than not have to bend to contingency.”
– Bilahari Kausikan
“Now everybody talks about China’s overcapacity in EV and solar, but I think what that brings with it is an abundance of ecosystem.”
– Chucheng Feng
“Even though we are in this period of global financialization, there’s actually been some very strong opportunities if you’re internationally diversified.”
– Joyce Chang