Session Summary
Today’s portfolios have outgrown Strategic Asset Allocation (SAA), and Total Portfolio Approach (TPA) responds by managing the fund as one portfolio.
SAA solved yesterday’s governance problem, but the world has moved on. Fixed weights such as 60/40, set by boards that meet four times a year, cannot keep pace with shifts in technology, demographics and geopolitics. The 2022 inflation losses on bond-equity portfolios pushed many boards to act.
TPA manages one portfolio towards one goal instead of ten asset classes. When each asset class optimises against its own benchmark, the whole fund can still lose. For example, an equity team that loses 18% when the market falls 20% may have “outperformed”, but the fund has still suffered a significant loss and is no closer to achieving its ultimate objective.
Every exposure is judged by what it adds to the whole portfolio. Asset owners should know the beta they own and buy it cheaply, paying alpha fees only for genuine alpha, not repackaged beta. External managers should be assessed on how they diversify the total portfolio, not on standalone metrics such as Sharpe ratios, back-tested returns or correlation to the S&P 500.
TPA is a governance model built on shared accountability, not an optimisation tool.
Be tight on purpose and loose on boundaries. TPA organisations are strict on the total fund goal, the whole-portfolio view of risk and accountability, and more flexible on asset class definitions and implementation. Greater discretion for the CIO must be matched by stronger risk guardrails and transparency.
Ownership and oversight are shared between the board and management. The model shifts from a top-down org chart (or RACI framework, which stands for Responsible, Accountable, Consulted, and Informed) to a Venn diagram where the two Os of the OREO framework (Ownership, Responsibility, Engagement, and Oversight) overlap. The question is less about who holds the power and more about who owns the outcome, and the answer is both the board and management.
Governance is the hardest pillar to change. Boards need to become genuine partners in the approach, yet SAA is familiar and comfortable. This “siren call” has led some funds to start the transition to TPA but then regress.
TPA is a multi-year organisational transformation that depends on people, incentives and patience.
Capability comes first, then structure follows. Returns now depend mainly on getting the overall portfolio right, which places a heavier burden on the CIO. Funds need not only robust risk models, but also the right talent and a stronger central portfolio team before taking on more discretion.
Incentives must match what people can control. Stop rewarding success within silos, but do not tie specialists’ pay to allocation decisions they cannot influence. Analysts are still measured against their benchmarks, portfolio leaders are held to the total fund mandate, and specialist insights flow up to inform allocation. Even with the right incentives, bias and ego make collaboration difficult, which takes time and humility to overcome.
There are no shortcuts to adopting TPA. TPA is not an end destination, but a spectrum of adoption, with institutions adapting the approach to their own circumstances and cultures. The most successful remain ambidextrous, retaining SAA as a tool rather than the centre around which the portfolio revolves, while recognising that meaningful transformation takes time.
Quotes
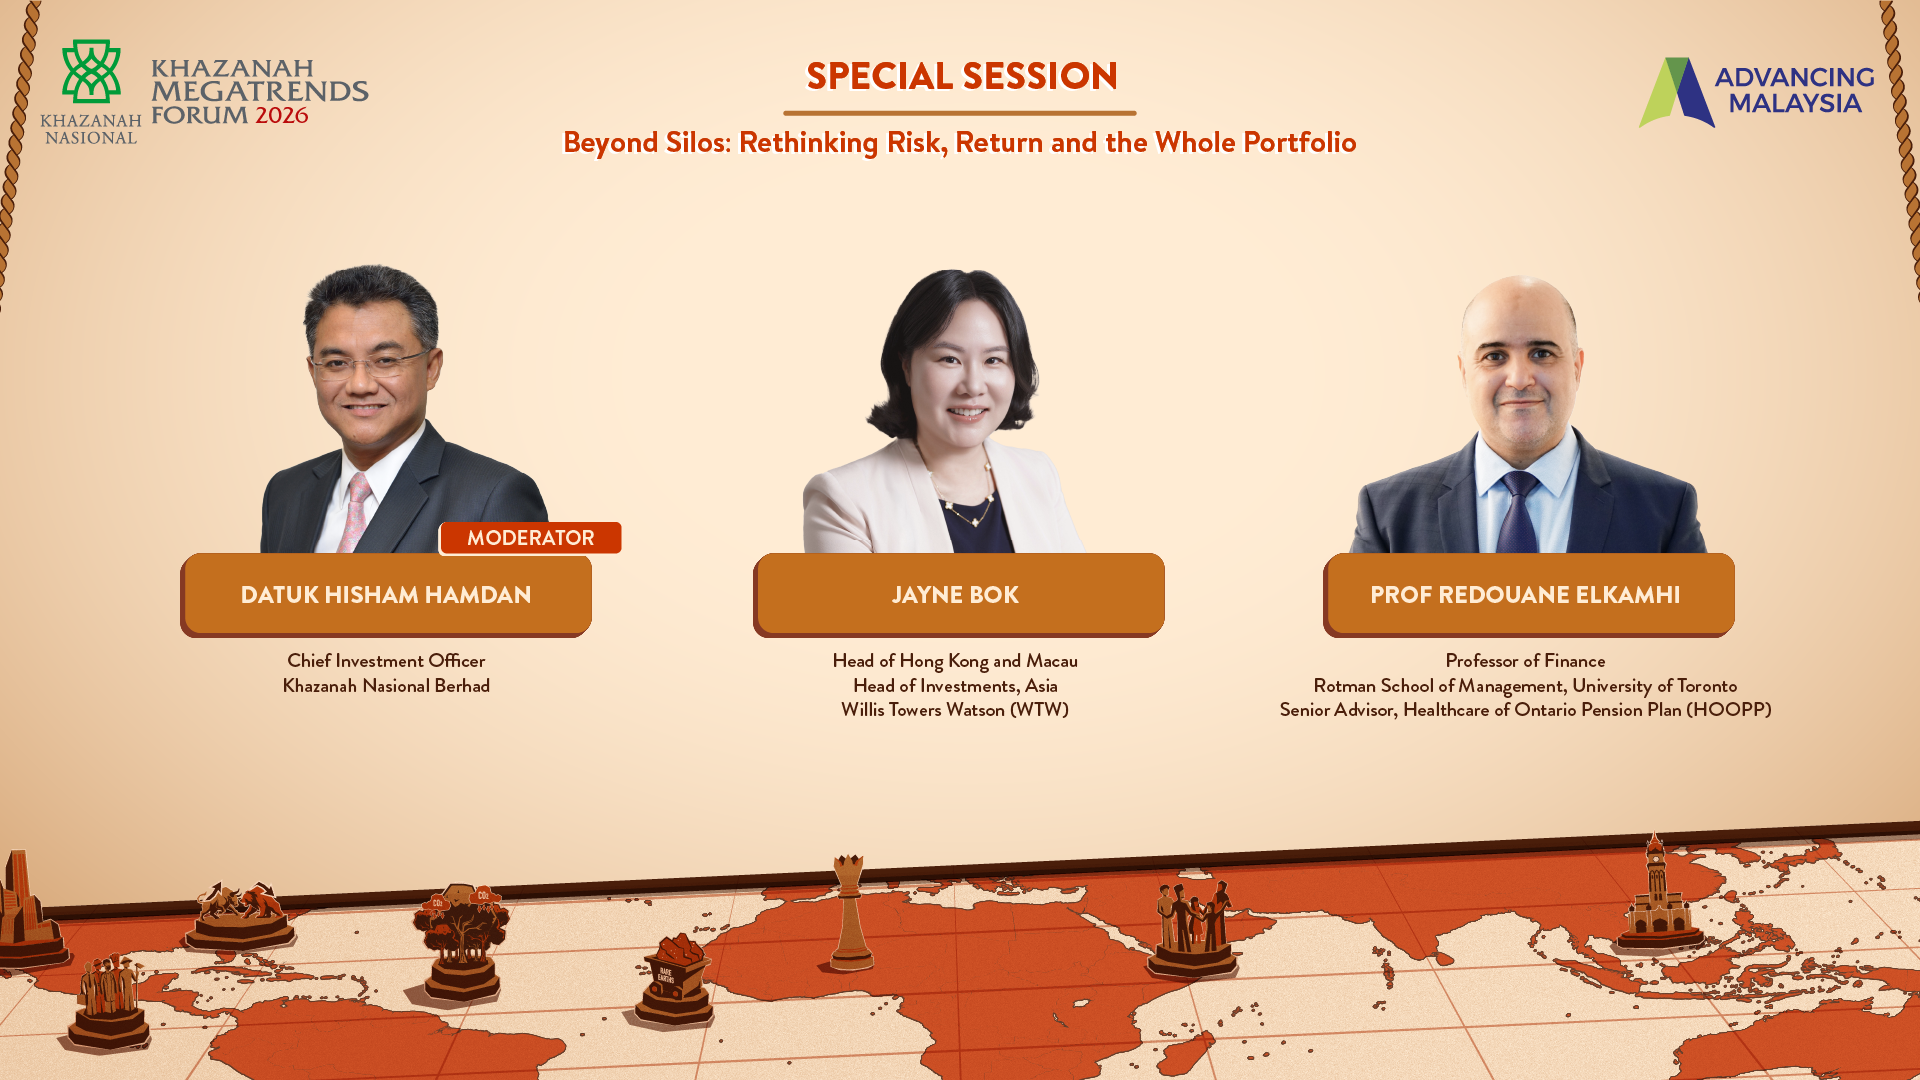
“The TPA mindset is more like OREO: Ownership, Responsibility, Engagement and Oversight. The two Os are very important because they need to be shared. It’s a tricky governance model to get right, but this concept of shared accountability is necessary to be successful.”
– Jayne Bok
“Coordination is easy to say, difficult to do. There is bias, inertia… and ego. The more you crush the ego, the more free you become. And that’s difficult to do. It takes time, it takes energy, it takes humbling, and it’s education.”
– Prof Redouane Elkamhi